
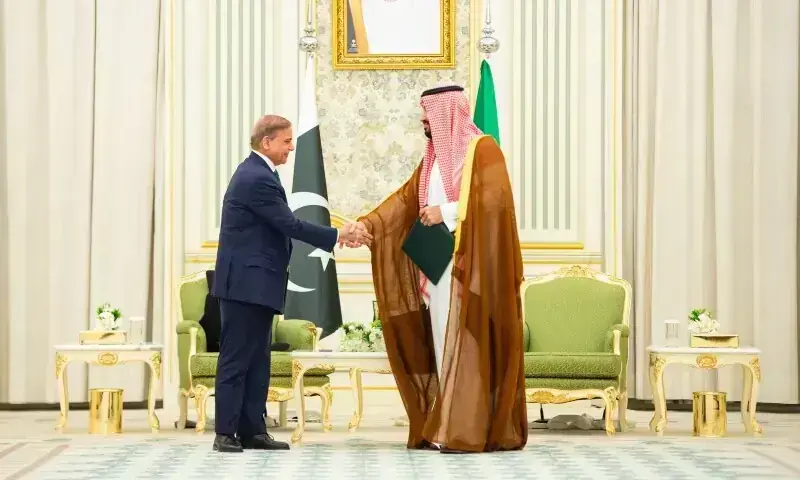
Pakistan has asked Saudi Arabia to provide $6.7 billion in oil financing over 15 years as the government seeks to manage rising fuel import costs and reduce pressure on its foreign exchange reserves.
On October 13, Finance Minister Muhammad Aurangzeb discussed the revival of Pakistan’s annual $1.2 billion deferred oil payment facility with Sultan Abdulrahman Al-Marshad, chief executive of the Saudi Fund for Development (SFD). The meeting took place on the sidelines of the World Bank and International Monetary Fund (IMF) annual meetings in Thailand.
According to reports, Saudi Arabia is reviewing Pakistan’s request. However, no final agreement has been announced. The proposed long-term financing would help Pakistan pay for oil imports over a longer period instead of meeting the full cost immediately.
Saudi Arabia has supported Pakistan through deferred oil payments since 2019. The previous $1.2 billion facility was signed in February 2025 and expired in April 2026. It carried an interest rate of 6%, according to government officials.
Pakistan’s petroleum import bill increased by 5.8% to $16.8 billion in the fiscal year 2025-26. Crude oil imports alone cost $7.2 billion, marking a 32% increase.
The IMF has not included the proposed Saudi financing in its projected inflows for Pakistan for the 2026-27 and 2027-28 fiscal years. The deal, if approved, could help Pakistan manage future oil payments and external financing needs.

