Beyond the Label: Why TAC Reinforces Solar’s Shift Towards Back-Contact Technology
The solar industry’s next major technological transition is increasingly converging around back-contact, or BC, cell architecture.
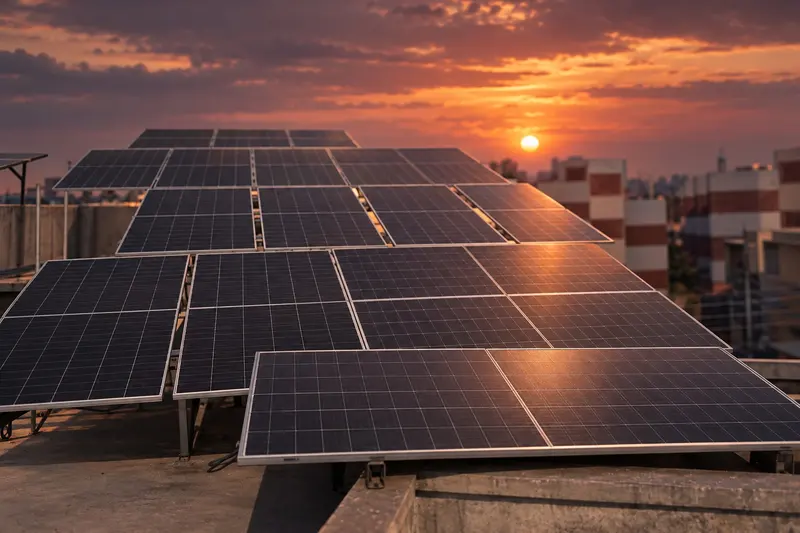
The solar industry’s next major technological transition is increasingly converging around back-contact, or BC, cell architecture.
That direction came into sharper focus on 17 October 2026, when JinkoSolar unveiled its new TAC technology alongside the Tiger Neo 5.0 residential module at its Global Technology Day in Shanghai. The 48-cell module was presented with power output of up to 510W and module efficiency of up to 25.52%.
Beyond the headline specifications, however, TAC raises a more significant industry question.
Should it be viewed as an entirely separate solar technology, or as another technological route within the broader back-contact family?
The distinction matters because terms such as TOPCon, HJT and BC are often discussed as though they represent directly competing technologies at the same level. In reality, they describe different aspects of solar-cell design.
TOPCon and HJT primarily refer to approaches used for contact passivation and reducing carrier recombination. Back-contact, by contrast, describes the physical architecture of the cell — specifically, where its electrical contacts are located.
In conventional solar cells, metal gridlines are positioned across the light-receiving surface to collect current. While necessary for that architecture, these gridlines also occupy part of the active surface and create optical shading.
Back-contact architecture relocates the electrical contacts to the rear of the cell. By removing front-side metallization, more of the surface can be used for light absorption, creating greater room for efficiency improvement when combined with advanced passivation, materials and manufacturing processes.
This is where TAC becomes particularly significant.
According to the technical description referenced in the source material, TAC adopts what has been described as a “2+1” architecture: HJT-based passivation in the P-region, TOPCon tunnel-oxide passivation in the N-region, and a front-side metal-free electrode structure with electrical contacts positioned on the rear.
The first two elements describe passivation approaches.
The third defines the underlying cell architecture.
From this perspective, describing TAC as a hybrid technology is technically meaningful when discussing its passivation methods, materials or manufacturing process. But combining TOPCon and HJT passivation does not, in itself, place TAC outside the BC category.
If both electrical polarities are contacted from the rear while the front surface remains free of metal gridlines, the underlying structure remains consistent with the fundamental definition of a back-contact cell.
The source material also points to an August 2026 patent application from a JinkoSolar subsidiary titled “Back-Contact Cell, Back-Contact Tandem Cell, and Photovoltaic Module,” providing additional evidence of the company's work around rear-contact architectures.
The bigger story, however, is not simply how one technology is classified.
It is what TAC says about the direction in which the photovoltaic industry is moving.
From Competing Labels to Architectural Convergence
For years, JinkoSolar has been closely associated with N-type TOPCon technology and, according to the source material, holds more than 700 authorized TOPCon patents globally.
The introduction of a next-generation platform incorporating a front-side metal-free, rear-contact structure is therefore significant beyond a single product launch.
Rather than showing that TOPCon, HJT and BC are mutually exclusive technology pathways, TAC demonstrates how advanced passivation approaches can increasingly be incorporated within back-contact architectures.
That distinction is central to understanding the next stage of solar-cell development.
BC is not necessarily a replacement for every passivation technology beneath it. It is an architecture within which different passivation techniques and manufacturing approaches can continue to evolve.
And JinkoSolar is not alone in moving in this direction.
Across the photovoltaic industry, leading manufacturers are developing their own approaches to rear-contact technology: LONGi with HPBC and HIBC, AIKO with ABC, Trina Solar with THBC, JA Solar with HBC, Tongwei with TBC, and now JinkoSolar with TAC.
The technologies differ considerably in process design, maturity, performance and commercial scale. Yet their emergence points towards a common architectural direction: relocating electrical contacts away from the light-receiving surface of the cell.
LONGi’s Early Bet on Back Contact
For LONGi, this direction is not new.
The company identified BC as a major future pathway for crystalline-silicon photovoltaics several years ago and has since moved from technology development into large-scale commercialization.
According to the source material, LONGi has been mass-producing BC products since 2022 and has accumulated more than 630 patents related to BC technology.
During the first half of 2026, LONGi’s BC module shipments reached 19.55GW, representing more than 65% of the company’s total module shipments during the period.
Those figures are significant because the transition toward a new photovoltaic architecture is ultimately determined not only by laboratory efficiency, but by the ability to manufacture reliably and competitively at scale.
LONGi Chairman Zhong Baoshen has previously argued that BC technology would become increasingly mainstream across crystalline-silicon photovoltaics. The growing number of manufacturers now developing rear-contact platforms suggests that this direction is moving progressively closer to an industry-wide trend.
TAC therefore matters not because it represents the same technology as LONGi’s HPBC or HIBC platforms — it does not.
Each technology has its own architecture details, process routes, materials and performance characteristics.
What TAC reinforces is the broader principle behind LONGi’s long-term technology strategy: that removing front-side metallization and moving electrical contacts to the rear provides an important platform for the next generation of high-efficiency crystalline-silicon solar cells.
From Technology Development to Market Adoption
The shift is also beginning to extend beyond manufacturers.
According to the source document, centralized utility-scale procurement programmes in China have introduced dedicated categories for BC products, with BC representing a growing share of certain procurement lots.
This is an important development.
A technology transition becomes commercially significant when it moves beyond laboratories and product announcements into manufacturing capacity, shipments and procurement requirements.
That process is now underway for BC.
It does not mean that front-contact technologies will disappear immediately.
Solar manufacturing operates at enormous scale. Production lines, equipment investments, supply chains, technology maturity, customer requirements and different market applications mean that multiple architectures will continue to coexist.
TOPCon, in particular, remains one of the industry's most important high-efficiency technologies and will continue to play a major role in global solar deployment.
Continued investment in TOPCon should therefore not be interpreted as evidence against BC. Industrial technology transitions are rarely instantaneous. Established technologies can remain commercially important even as manufacturers invest in architectures intended to push the next stage of performance.
The more revealing signal is where new research, product development and manufacturing investment are moving.
And increasingly, several major manufacturers are exploring different routes toward the same fundamental architectural idea.
Technology Labels Matter Less Than Module Performance
For customers, investors and developers, none of this means that the letters attached to a technology should become the sole basis for choosing a solar module.
Whether a product is labelled TAC, HPBC, HIBC, ABC or something else, the performance of the complete module remains what ultimately matters.
Efficiency, energy yield under real operating conditions, temperature behaviour, degradation, mechanical reliability, long-term durability, warranty support and lifetime electricity generation all remain critical.
Two technologies belonging to the same broad BC family can still perform very differently because of variations in cell design, passivation, metallization, materials, module construction and manufacturing quality.
Being part of the BC family therefore does not make different products technologically identical.
But equally, creating a distinctive commercial name for a technology does not necessarily place it outside the broader architectural family to which it belongs.
That is why the most important story surrounding TAC is not a debate over terminology.
It is the broader convergence it represents.
Different manufacturers are approaching the challenge through different passivation technologies, process routes and proprietary designs, but a growing number are arriving at the same fundamental architectural principle: moving electrical contacts away from the light-receiving surface and onto the rear of the cell.
LONGi made that direction a central part of its technology strategy years ago and has already moved BC from R&D into large-scale commercial production.
The emergence of TAC therefore does more than introduce another name into the solar technology landscape.
It reinforces the case that back-contact architecture is moving from an alternative technology pathway toward one of the defining platforms for the next generation of crystalline-silicon photovoltaics.
Share this story
Send it to someone who should read it.