
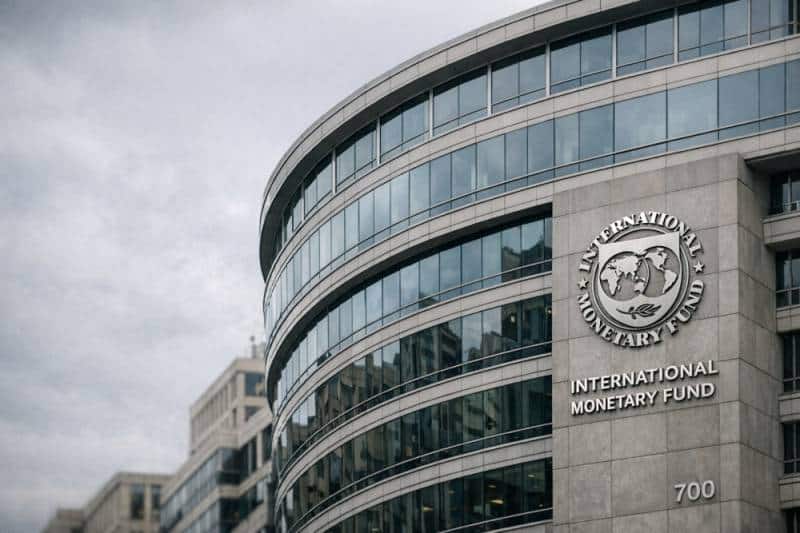
The International Monetary Fund (IMF) has expressed satisfaction with Pakistan’s economic progress as its mission begins the fourth review of the country’s $7 billion Extended Fund Facility (EFF) programme.
During meetings in Karachi, State Bank of Pakistan (SBP) officials briefed the IMF team on foreign exchange reserves, monetary policy, imports, the exchange rate and other external sector developments. Officials told the mission that Pakistan had achieved its target of keeping foreign exchange reserves above $17 billion. The briefing also covered the current account position and rising foreign direct investment.
The positive assessment comes despite renewed pressure on prices. According to the Pakistan Bureau of Statistics, consumer inflation reached 11.15% year-on-year in August 2026, compared with 3.1% in the same month last year. Monthly inflation also rose by 1.19%.
The IMF team is now moving to Islamabad, where formal policy-level discussions with Pakistan’s economic team are expected to begin. The review will assess progress against the targets and reforms agreed under the programme.
The IMF had earlier said Pakistan’s strong policy implementation had helped maintain economic stability, while stressing the need for continued reforms.

